Which Asset Vantage Alternatives Could Replace the Books, and Which Add Reporting?
Compare Asset Vantage alternatives for US family offices by the job they need to do: replace accounting books, add reporting, or connect both. Use one entity-to-report case to test the proposed role.
These Asset Vantage alternatives take on different jobs. FundCount, Eton Solutions AtlasFive and Archway describe general-ledger platforms that a family office could investigate as a new accounting backbone. Addepar and Masttro emphasize consolidated investment data and reporting. Aleta describes an investment ledger alongside links to specialist general ledgers; Asora describes asset-level accounting data and reporting. The right shortlist depends on whether your office needs to move its books, improve what sits above them, or both. A product description cannot establish that the proposed configuration will replace your current system.
- Name the record you may replace: legal-entity books, investment positions, or principal reports.
- Give every candidate the same dated entity-to-report case and judge it against the role you propose to buy.
- Separate what a demo shows from what the US contract covers and what a parallel run proves.
01What Does Asset Vantage Already Cover?
Asset Vantage presents itself as a combined general-ledger and performance-reporting platform for family offices. Its described scope includes investment and accounting books, data aggregation, multi-entity views and reports. An alternative is comparable only after the office identifies which of those jobs its current configuration actually performs.
The Accounting and Entity Record
For a finance team, “replace Asset Vantage” may mean moving the chart of accounts, legal-entity balances, intercompany activity, investment lots, approval history and month-end close. Those records have owners and reconciliation rules. A dashboard that reads an exported balance is useful, but it has not thereby become the system that maintains the balance.
List the entities and books in scope before naming a vendor. Record where journals are posted, who approves valuation changes, which system owns cost basis and how a period is locked or reopened. Asset Vantage's own pricing page distinguishes a reporting-oriented package from a package that lists integrated and inter-entity accounting; the exact module you use matters more than the broad platform label.
Aggregation, Reporting and Delivery
The other job is gathering bank, custodian and private-asset data and turning it into entity, family and investment reports. If the books are sound but principal reporting is slow, a reporting layer may be added without moving the formal close. That route still creates work: feed mapping, approval of source values, reconciliation of reports to the books, recipient access and a clear owner for exceptions. See our family-office financial software map for the broader system boundaries.
02How Were These Alternatives Chosen?
This shortlist is conditional and unranked. A candidate belongs here when its current public material documents a relevant family-office accounting, investment-data or consolidated-reporting job. Inclusion does not mean every capability is native, included in a base subscription, available for every US office or equivalent to Asset Vantage's configured workflow.
Which Products Qualify for This Shortlist?
We retained seven named platforms with a plausible role in the same family-office workflow: Addepar, Aleta, Asora, AtlasFive, FundCount, Masttro and Archway. Broad software directories also surface personal portfolio tools and general business accounting apps. Those may solve a narrow task, but a holdings dashboard alone does not establish legal-entity accounting, and a small-business ledger alone does not establish alternatives data or ownership look-through. That is why a category label or review score is not our inclusion test.
What Can Public Evidence Establish?
Product pages can establish what a vendor describes; they cannot establish a successful migration, entitlement to a module or a result on your data. “Not established on the pages reviewed” means unknown; absence cannot be inferred. All product-source descriptions below were checked on 14 October 2026. The same questions apply to every candidate: what record could it own, what reporting can it produce, what must connect from elsewhere, what is included in the quoted package and what can the buyer observe in a demo?
03Which Jobs Need a New Ledger, and Which Need a Reporting Layer?
Start with the failure the office needs to correct. If journals, entity balances, intercompany positions or the close are unreliable, investigate a platform that describes those books and test its posting and control workflow. If the accounting record is reliable but holdings arrive late or family reports are hard to assemble, investigate aggregation and reporting while keeping the ledger. Some candidates straddle that line. Classify the proposed deployment for each buyer; a platform may occupy both roles.
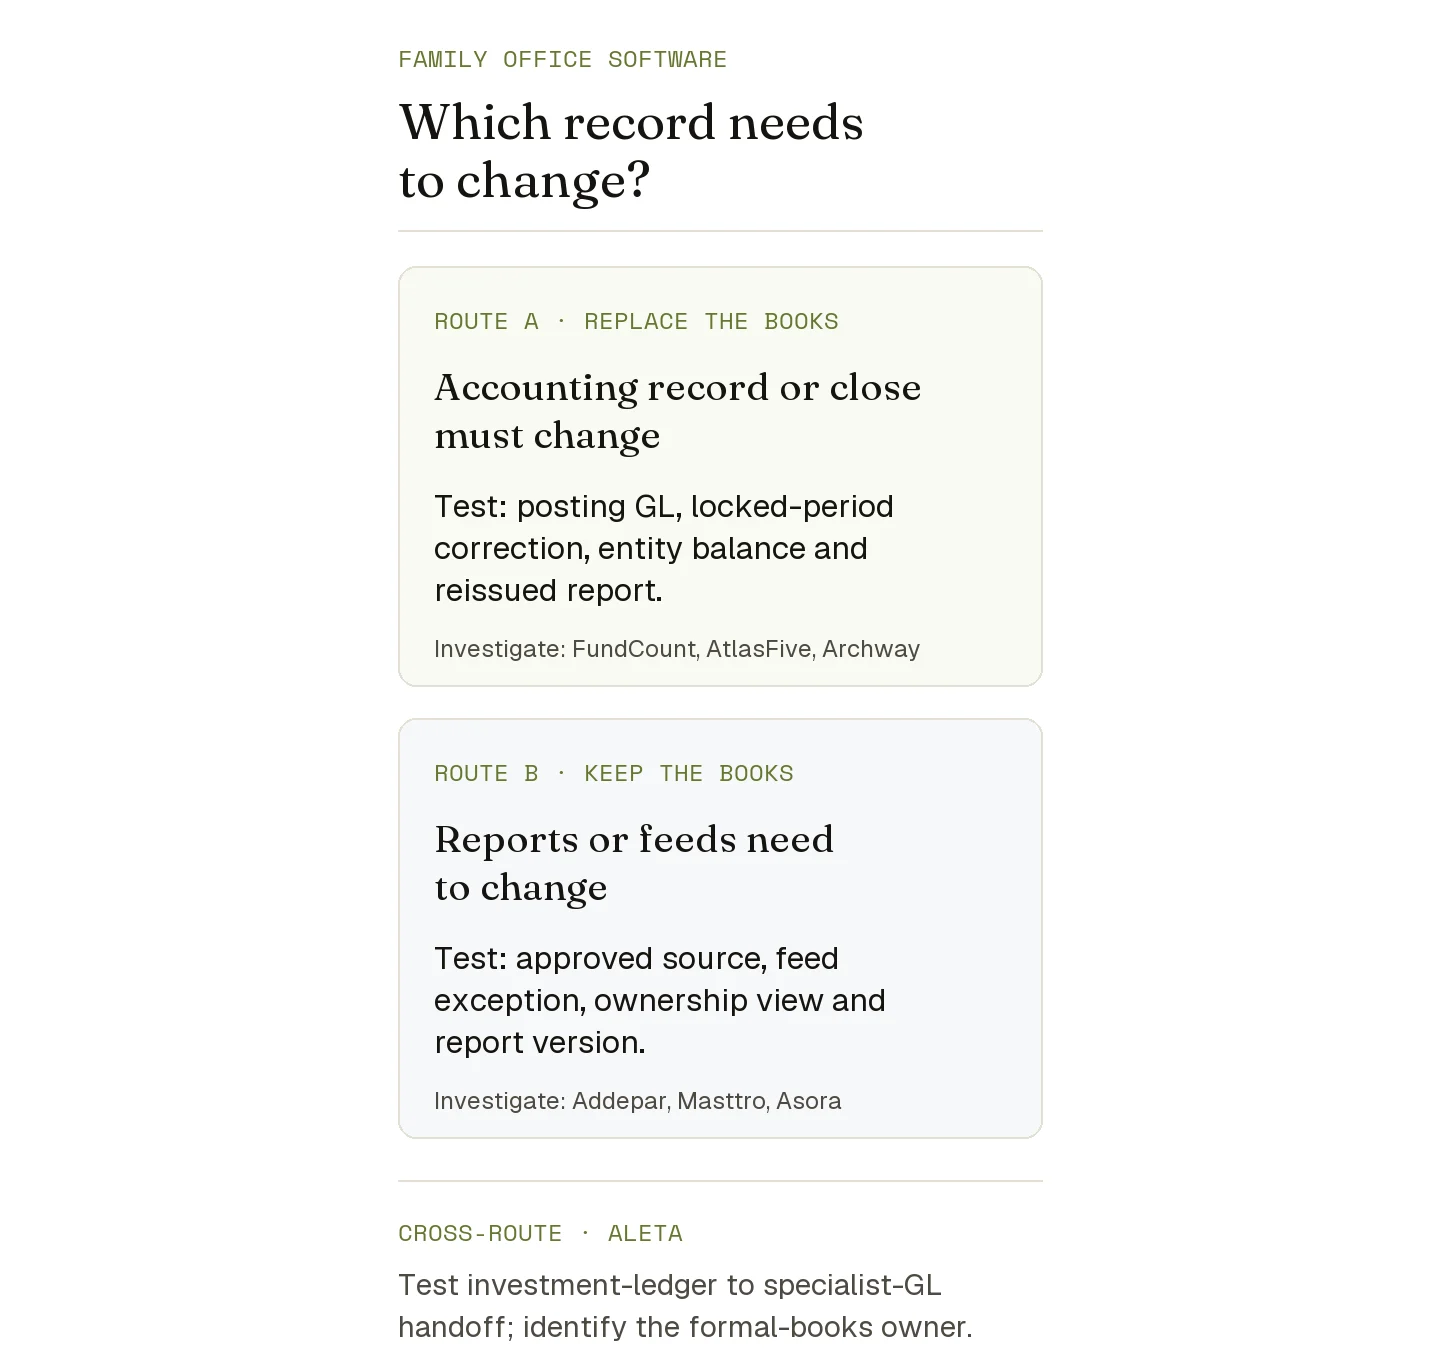
These are candidates to investigate, not verified fits. Test the same correction and report trail before choosing a route.
If the Accounting Record Must Change
Ask the proposed ledger owner to accept transactions and adjustments, show the legal-entity entry, reconcile balances, eliminate internal positions in the required group view, preserve approvals and reissue the dependent report. A platform's claim to have a general ledger earns it a place in the test; it does not prove your chart of accounts, partnership rules or close controls are covered.
If the Books Stay but Reporting Must Change
Ask the proposed layer to ingest approved balances and source dates, map entities and ownership, flag an unreconciled feed, and show which report recipients can see a corrected value. It need not invent a journal if another system owns one. It does need to tell the reader where each reported number came from and how discrepancies return to the accounting owner.
Compare Accounting, Entity, Data and Control Evidence
Each column below answers one question. D means the vendor describes that function within its platform; U means the reviewed page does not establish the function. These are states of public descriptions, not buyer test results. Every candidate remains untested on the illustrative case. A D does not mean equal depth across vendors, inclusion in a quote or a passed demo. A U never means the feature is absent.
| Candidate | Posting Legal-Entity GL Described? | Entity or Ownership Function Described? | Investment Data and Reports Described? |
|---|---|---|---|
| Addepar | U: replacement posting GL unestablished. | D: ownership look-through. | D: multi-source investment data and reports. |
| Aleta | U: posting formal entity books unestablished. | D: investment data across entities; ownership look-through unestablished. | D: investment ledger, reconciliation, analytics and reports. |
| Asora | U: posting entity GL unestablished. | D: multi-entity structures; ownership look-through unestablished. | D: asset-level book cost, gains, aggregation and reports. |
| AtlasFive | D: GL and trust accounting. | D: entity management. | D: portfolio and reporting workflows. |
| FundCount | D: portfolio, partnership and GL accounting. | D: family-entity consolidation. | D: aggregation, reporting and portal. |
| Masttro | U: posting entity GL unestablished. | D: entity and asset map. | D: feeds and consolidated reports. |
| Archway | D: family-office and fund GL. | D: entity look-through. | D: feeds and reports. |
For all seven candidates, the reviewed public pages leave the specific correction-approval and report-reissue trail U: unestablished. The buyer must test it in the same case. Documented dependencies differ: Addepar describes existing-GL integration, Aleta describes a flow into specialist GLs, AtlasFive names an integrated partnership-accounting module, and Archway describes outsourced operations. Those facts do not establish who approves a correction or whether a report can be reissued. The profiles below identify the relevant boundary for each candidate.
Use the case below to turn each U or conditional D into a question with an observable artifact. A ledger proposal must show the approved entry, entity balance and report trail. A layer proposal must show the approved source, reconciliation and report trail. For a connected or outsourced function, ask which party operates it and where the handoff is recorded.
04Seven Asset Vantage Alternatives to Investigate
Compare the work your office would assign to each system.
Addepar
Addepar's family-office page describes consolidation across custodians, illiquid assets and legal entities, with look-through reporting and API connections to existing general ledgers. Its distinctive question is whether the current bottleneck is the principal's investment view across structures while another system retains the books. Ask the demo team to show where a corrected entity balance is approved and how Addepar marks the report as reconciled to it. Its reviewed family-office page did not provide a software price or a promise that it replaces every legal-entity accounting task; obtain package and implementation scope in writing.
Aleta
Aleta's accounting-ready page describes an internal double-entry investment ledger, reconciled wealth data and flows into specialist general ledgers. An office seeking to move formal entity books should treat this as a two-system proposal until the vendor demonstrates otherwise: identify the posting owner, integration, reconciliation and support agreement for the specialist GL. In a demo, make the team show an investment adjustment, its posting boundary and the linked GL's balance after transfer. Aleta advertises a $1,000/month starting price; confirm US scope, data services, integrations and any additional charges in a proposal.
Asora
Asora describes multi-entity aggregation and reporting. Its accounting page specifically describes income, gains, fees and tranche-level book-cost tracking, giving an investment team a way to inspect cost and gain figures behind reports. A posting ledger for the office's legal entities remains unestablished on that page. Asora merits a reporting-focused demo when the main problem is asset visibility; ask who owns journals and formal balances. Its US-dollar pricing selector displayed $15,600/year for the selected $50 to $100 million net-worth-under-management bracket, plus a one-time implementation charge described as 25% of the annual subscription; confirm eligibility, account packs and additions for your structure.
Eton Solutions AtlasFive
AtlasFive describes a broad operating platform spanning entity and portfolio management, integrated general ledger, trust and partnership accounting, transactions, documents and reporting. That breadth makes it a candidate when moving the accounting backbone would also change several office workflows. It increases the importance of module and service boundaries: request a proposal that identifies the accounting modules, integrations, data migration and ongoing work the team would still perform. In the demo, trace one corrected transaction to the entity books and family report, including the required approvals. The reviewed page did not state a comparable public price or go-live commitment.
FundCount
FundCount describes one ledger beneath portfolio and partnership accounting, consolidated family reporting, data aggregation and an investor portal. It belongs in a ledger shortlist when the office wants accounting and investment reports to reconcile from one foundation. Its differentiator to test is whether the quoted family-office package covers the relevant entity elimination, partnership allocation and principal report together. The Single Family Office page displayed a $35,899/year starting figure on 14 October 2026, with digital-transformation and hosting fees applying. Confirm the billing currency, US terms, configuration and migration costs in a written quote.
Masttro
Masttro describes a live map of entities and assets, direct feeds, alternatives data and consolidated reports. It is a reporting-route candidate when the office can keep its books but needs a clearer view across custodians, private investments and family structures. The demo must show how a changed source value is accepted, reconciled and reflected in a report, and who corrects the formal ledger if it differs. The reviewed page leaves a formal posting GL unverified. Masttro's pricing page requests a tailored proposal and says pricing is not AUM-based; it does not give an amount. For a closer comparison of these choices, see our Masttro alternatives analysis.
Archway (Formerly SEI Archway)
The current Archway site describes a general ledger, direct feeds, entity look-through, investment reports and outsourced services delivered by its team. SEI's July 2025 release says Aquiline acquired its Family Office Services business and it now operates as Archway. The platform deserves a ledger-route look when accounting, reporting and who performs the work may change together. Its differentiator is the software-versus-service decision: specify which functions your office will operate and which Archway staff will perform. Trace one entry through the required report, then put data ownership, approval roles and service levels in the contract. No comparable public price was stated on the reviewed product page.
05Follow One Illustrative Entity-to-Report Case Through the Shortlist
Use one set of records for every demo, and state the accounting assumptions before judging an answer. The figures below are illustrative; no vendor has run or passed this test for us. Use the case to test each proposed role. The office's own policy determines its accounting treatment.
Start With the Same Source Records and Ownership Structure
Imagine a family owns 100% of Oak LLC and Pine LLC. These are the only assets and liabilities in this US-dollar exercise: no tax, currency, minority-interest or other adjustment. At 30 June, Oak has $1,000,000 cash and a $200,000 receivable from Pine. Pine has $500,000 cash, a private-fund holding recorded at $2,000,000 and an equal $200,000 payable to Oak. Oak's net assets are $1,200,000; Pine's are $2,300,000. The combined family view is $3,500,000. Eliminating the internal pair removes $200,000 from gross assets and $200,000 from gross liabilities; it does not subtract $200,000 from net assets.
Assume the June period was locked on 5 July and the first $3,500,000 family report was issued. On 10 July, the fund administrator supplies a corrected 30 June value of $2,150,000. For this exercise, the office's policy requires the controller to approve a $150,000 June adjustment, preserve the original close record, and reissue the report after the amended period is locked. Pine's net assets then become $2,450,000 and the combined view becomes $3,650,000; cash remains $1,500,000 across the two entities. Give every vendor the original and corrected statement, both dates, the due-to/due-from pair, the entity map, the lock state and the office's approval rule. Then send an old $2,000,000 value through a delayed feed: the system should flag the $150,000 conflict, preserve the approved value and assign the exception to an owner.
For a separate ownership-mapping pass, add Cedar LLC, which has $500,000 of external net assets, no transactions with Oak or Pine and a 40% family economic interest held outside Oak and Pine and absent from their books. The family's attributed exposure to Cedar is $200,000. A look-through report that includes it would show $3,850,000 of illustrative economic exposure after the Pine correction. Keep that measure separate from the $3,650,000 Oak/Pine combined-book view. This exercise does not prescribe how Cedar should be recognized or consolidated in financial statements.
Check the Ledger Result, Entity Rollup and Principal Report
A candidate proposed as the book of record should show who authorized the closed-period change, how the June adjustment was posted and the period relocked, the changed entity balance, the intercompany treatment and the new report version. If its workflow cannot satisfy this exercise's policy, record that limit and the resulting reconciliation rather than silently changing a dashboard number.
A candidate proposed as a reporting layer may instead receive the corrected Pine balance from the existing ledger after its controller-approved closed-period change. It should show the 30 June effective date and 10 July receipt date, identify the approver and approval record in the source system or its own workflow, preserve the original source, produce the $3,650,000 Oak/Pine view only after approval, and identify who handles any $150,000 difference between its data and the books. Both roles must make the delayed feed visible and retain the approved value. The Cedar extension tests whether ownership attribution is shown separately from the book total. Displaying $3,650,000 or $3,850,000 alone cannot establish the required trail or a GAAP consolidation conclusion.
Use a Role-Specific Demo Scorecard
Bring this blank scorecard to each demo. Record the observed screen, export or audit record as evidence; a verbal assurance leaves the result unknown. Mark unknown when the task was not demonstrated; unknown is neither pass nor fail.
| Same Question for Every Candidate | Pass Evidence if Proposed as Ledger | Pass Evidence if Proposed as Reporting Layer | Result to Record |
|---|---|---|---|
| Who approves the closed-period correction and effective date? | Controller approval, June adjustment, relock and preserved original close history. | Named approver and approval record in the source ledger or layer, linked to the imported value, both dates and provenance. | Pass / Fail / Unknown, with artifact. |
| How does the family view reach $3,650,000? | Oak $1.20m + Pine $2.45m, with the internal pair handled under the reporting policy. | Same view reconciled to approved books and entity mapping. | Pass / Fail / Unknown, with artifact. |
| What happens when the delayed feed brings back $2,000,000? | $150,000 break appears; approved book value stays until an authorized entry; exception owner recorded. | $150,000 conflict appears; approved report stays; source and escalation owner recorded. | Pass / Fail / Unknown, with artifact. |
| How is Cedar's 40% interest shown? | Entity books and ownership record remain distinguishable from the $200,000 attributed exposure. | Look-through adds $200,000 to economic exposure without relabeling it as Oak/Pine book net assets. | Pass / Fail / Unknown, with artifact. |
| What happens to the former $3,500,000 report? | Prior and reissued versions identifiable, with recipient access. | Prior and reissued versions identifiable, with recipient access. | Pass / Fail / Unknown, with artifact. |
The scorecard tests one controlled correction. It does not cover every asset type, permission rule or partnership allocation. Add those cases if they are material to the office's actual replacement decision.
06When Should You Keep Asset Vantage and Add a Layer?
Keeping the current books avoids a ledger migration when the close is trusted and the unmet need is faster aggregation, ownership views or more usable reports. The added layer still requires interface and reconciliation work. It succeeds only if it receives approved data, exceptions return to a named owner and readers can reconcile the new output to the authoritative records.
Separate a Reporting Problem From an Accounting Problem
Ask the controller and principal to identify one failed month-end or quarterly decision. If the journal, entity balance or cost basis is wrong, a prettier report will carry the error forward. If the balances are right but the family waits weeks to combine custodians and private assets, replacing the ledger may impose migration work without solving the main bottleneck. Test that distinction with one dated exception before discussing platform breadth.
Map the Records, Interfaces and Owners That Would Remain
For an added layer, write down the source system for positions, valuations, legal-entity balances and documents; the transfer method and frequency; who can override a value; who resolves breaks; and which report is authoritative for each audience. Include termination and export terms so the office can retrieve both the records and their history. The added subscription's cost is only part of the decision: ongoing reconciliation and dual-system support belong in the same comparison.
07What Must Be Confirmed Before a US Contract or Migration?
Treat a live demo, a written proposal and a parallel run as three different decisions. A demo can show a task on a controlled sample; a contract determines whether your configuration and services are included; a parallel run tests selected real outputs and the controls included in that run.
Request the Same Role-Specific Demo Evidence
Send the source files and expected $3,650,000 result in advance. For a ledger proposal, request the adjustment record, entity trial balances, intercompany treatment, approval log and report version. For a reporting-layer proposal, request the import record, source dates, reconciliation to the retained ledger's approved corrected June balance, exception queue and report-access log. Ask whether each result was native, configured, integrated, outsourced or manually prepared for the demo.
Compare Modules, Services, Prices and US Delivery in Writing
Ask each provider to price the same entity count, accounts, users, feeds, history, report set and support level. State whether the office or vendor performs data cleansing, reconciliation, report design and ongoing exception work. The public figures above are not comparable totals: Aleta's advertised monthly start, Asora's selected bracket plus implementation charge and FundCount's annual starting figure with additional fees describe different packages. Asset Vantage's visible pricing page shows INR examples subject to GST and quarterly revision, which do not establish the price of a US deployment. For every vendor, request currency, tax, one-time and recurring charges, module entitlements, hosting, implementation milestones, US support hours and exit/export terms. Published go-live claims cannot establish the schedule for this office's data and entity structure.
Use a Parallel Run Before Retiring Any Record System
As a buyer gate, run at least one representative reporting period through both paths. Reconcile opening balances, transactions, valuations, entity totals and final reports; record every unexplained difference and the person who owns it. Keep the former system and its audit history available until the finance owner accepts the new books or, for an adjunct, the new reports. One clean illustrative demo supports further diligence; a cutover requires evidence from the office's own parallel run and its tested controls.
08Which Shortlist Fits the Work You Need to Change?
The shortlist should follow the record that must change. Retain candidates while their documented role fits; narrow the list using the common test, written scope, total cost, US delivery and contractual fit. A product with broad features can still be wrong for a particular entity structure, staffing model or reporting obligation.
If the Accounting Backbone Must Change
FundCount, AtlasFive and Archway each describe a general ledger, but they invite different checks. FundCount connects investment and partnership accounting to one GL; confirm that the quoted package covers the office's allocation and consolidation work. AtlasFive spans trust, partnership, document and transaction workflows; confirm the modules and implementation the office would actually use. Archway combines software with available outsourced operations; assign posting and approval duties between its team and yours. Aleta belongs on this route if the proposed two-system arrangement demonstrates formal entity posting, integration, reconciliation and support with the specialist GL, or if the vendor demonstrates native formal books. Require the same entry, approval, entity balance and report artifacts from each proposal.
If the Books Stay but Reporting Must Change
Addepar describes ownership look-through and connections to existing GLs; prioritize it for a multi-custodian investment view if the books can remain elsewhere. Masttro describes an entity-and-asset map and direct feeds; test exception handling across the office's institutions. Asora documents multi-entity reporting and tranche-level book cost; ask how its figures reconcile to formal books. Aleta adds an investment ledger and a described external-GL flow; evaluate it as a two-system route when that handoff is acceptable. Other platforms here may also be offered as layers. If fund-level allocations and investor statements matter, test them separately using our fund reporting software comparison. Preserve the current accounting owner and take the same fixture and blank scorecard to every shortlisted demo. Narrow the list from observed artifacts and written duties, then decide from a parallel run.
The coming shake-out in family-office software
The category has never been more crowded. Consolidation is coming — and the firms that survive will be… Knowledge & Decision · Analysis
Is a Multi-Family Office Right for Your Family? Compare Fit, Fees and Services
Compare multi-family office fit, services, fees and family responsibilities with an illustrative quote worksheet and provider-check questions. Knowledge & Decision · Analysis