The Release Decision in Family Office Investment Performance Reporting
A family office investment report is ready when its principal, investment committee and finance team can tell what changed, why it changed and…
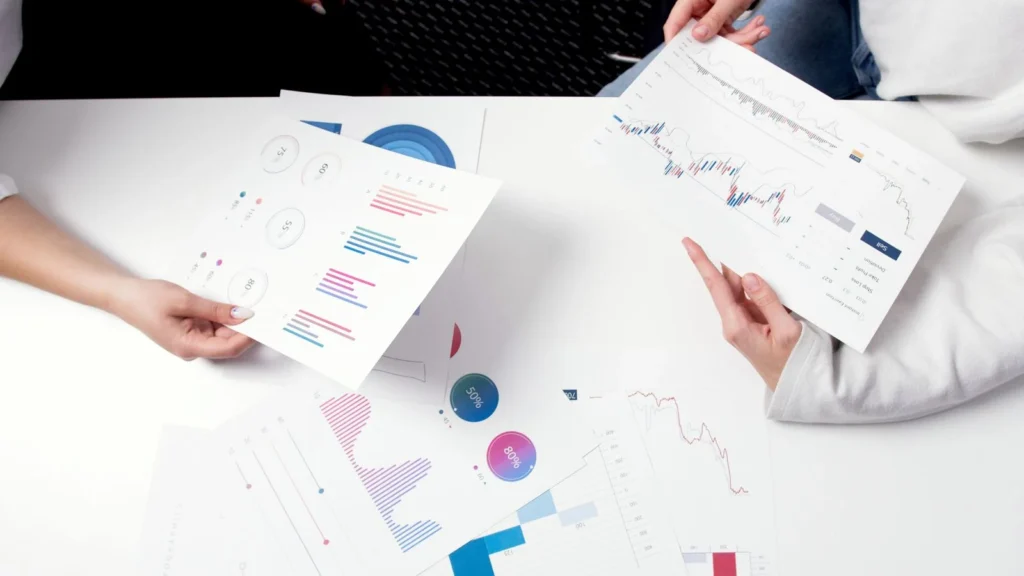
A family office investment report is ready when its principal, investment committee and finance team can tell what changed, why it changed and which figures remain provisional. A polished total return cannot answer those questions if an external contribution is treated as investment gain or a September private-fund valuation is presented as a December mark.
This guide works through one fictional year-end close. It tests a liquid portfolio's return, a private investment's valuation lag, benchmark choice and the approval needed before a family report goes out. The figures illustrate the method; they are not a family's results.
- State the question each number answers. Portfolio value, time-weighted return, money-weighted return, liquidity and private-investment multiples do different jobs.
- Trace material figures to dated sources. Reconcile positions, transactions, external flows, fees, FX and valuation dates before calculating and explaining a return.
- Release with visible exceptions. A stale private NAV, unmatched cash flow or incomparable benchmark needs an owner, a status and a decision about whether the pack may be issued.
01What the Report Must Let Each Reader Decide
The principal may want to know whether family capital is supporting near-term commitments. The investment committee needs to see performance against an agreed mandate and comparable benchmarks. The controller needs to know whether reported positions and cash flows agree with approved records. A single dashboard can serve all three only if it retains the underlying dates, scope and exceptions.
Start with a one-page decision summary: opening and closing values, external contributions and withdrawals, return methodology, benchmark, allocation and liquidity. Beside those figures, show the share of assets with current approved values and the items still under review. Then provide drill-downs by legal entity, account, manager and asset class. A consolidated family view must not erase which entity owns an asset or which account supplied a value.
| Report line | Minimum question before release | Record to retain |
|---|---|---|
| Closing value | Which date, currency, entity and valuation policy? | Custodian or approved private-asset valuation, with source date |
| Return | Which assets, period, fee basis and cash-flow treatment? | Reconciled position and transaction history plus calculation method |
| Benchmark | Does it cover the same period, currency and investable exposure? | Approved benchmark definition and data version |
| Liquidity | What is available after restrictions and known commitments? | Cash balances, credit terms, capital-call schedule and approval record |
| Exception | Who owns the missing or disputed input, and by when? | Dated exception and release decision |
The GIPS standards make consistent input data and calculation methodology central to fair performance presentation. This family-office example does not claim GIPS compliance; it borrows the discipline of defining the calculation before interpreting the result.
02Reconcile One Return Before Publishing It
Assume Rowan's liquid sleeve is worth US$10.0 million on 1 January. Immediately before a midyear external contribution, it is worth US$11.0 million. The family adds US$2.0 million, so the post-flow value is US$13.0 million. On 31 December, the sleeve is worth US$13.2 million. For this teaching example, the contribution occurs at the exact midpoint of the measurement year. Assume no other external flows, fees or FX movements, and that each value uses the same scope and approved pricing basis.
| Step | Liquid-sleeve value | What changed |
|---|---|---|
| 1 January opening | US$10.0m | Measurement begins |
| Midyear, before family contribution | US$11.0m | First subperiod gained US$1.0m |
| Midyear, after contribution | US$13.0m | Family added US$2.0m; this is not return |
| 31 December close | US$13.2m | Second subperiod gained US$0.2m |
The first subperiod return is 10.00%: US$11.0m divided by US$10.0m, less one. The second is 1.54%: US$13.2m divided by US$13.0m, less one. Linking them gives an illustrative time-weighted return of 11.69%: (1.10 × 1.0153846) − 1. The US$3.2m increase in closing value is not all performance; US$2.0m is the family's contribution.
The family's contribution arrived halfway through the year, so a money-weighted calculation gives that US$2.0m less time to earn a return. Under this exact-midpoint simplification, the annual money-weighted rate is approximately 10.93%: it solves US$10.0m × (1+r) + US$2.0m × √(1+r) = US$13.2m.
The two rates answer different questions about cash-flow timing. Real reports need actual transaction dates, fees, valuation policies and any other flows. Never infer a family-wide IRR by averaging the IRRs of separate funds; CFA Institute's discussion explains the aggregation problem.
Before the committee sees either rate, reconcile the custodian closing value, midyear contribution, fees, income, corporate actions and the report's asset perimeter. If the US$2.0m was an internal transfer from another included family account, it is not an external flow at the consolidated family level. The same movement can be external to the liquid sleeve and internal to the family total. Label the scope on every return.
03Show Private Assets Without Inventing December Values
Suppose the family also owns a private fund whose latest approved NAV is dated 30 September. The 31 December family pack may still need to show that holding. It must not relabel the September NAV as a December appraisal or present a refreshed return that has not been calculated from an approved value.
Record the 30 September source date, the amount then reported, any subsequent capital calls or distributions, the valuation policy and the next expected statement. The memo must say whether it displays the approved September NAV unchanged, with later cash movements on separate lines, or a reconciled cash-flow roll-forward with its own method, date and approval status. Neither convention is a new December appraisal. If the office makes an internal estimate, label its method, owner and approval status; do not place it beside final custodian prices as though the two have equal certainty.
For a private fund, show commitments, paid-in capital, distributions and remaining NAV with their dates. IRR and multiples can add context, but an unrealized valuation and a cash distribution are different evidence. Cambridge Associates says its private-investment benchmarks draw underlying information from quarterly fund financial statements. That illustrates why a private-market comparison can arrive on a different timetable from daily public-market pricing.
The release decision is not always binary. The office may issue a pack showing the last approved private NAV dated 30 September, while marking the 31 December value unknown and withholding a current consolidated return that needs it. Any aggregate value carrying that September NAV must say mixed-date, last-available values; it is not a current 31 December total. The office can give the committee a scheduled update.
If a mandate or family policy requires a current valuation, hold that figure or the entire report. Record the approver's choice; never quietly promote an estimate to final.
04Make Benchmarks Comparable or Mark Them Unavailable
A benchmark is useful only when the comparison describes the same decision. For a public-equity manager, record the index, currency, period, dividend treatment, fee basis and mandate exposure. A US-dollar portfolio compared with a local-currency index or a net-of-fees manager return compared with a gross index needs an explicit bridge or a caution label.
For private investments, a public index return is not a plug-in substitute for a vintage, strategy and cash-flow-aware comparison. A private benchmark also has a reporting lag and a defined sample. State the chosen basis and its limits, or leave the benchmark unavailable until the committee approves one. Do not choose the comparator after seeing the result.
Rowan's report therefore needs two benchmark decisions: one for the reconciled liquid sleeve and one for the private holding when comparable data exist. A single blended benchmark is optional only if its weights, rebalancing rule, data dates and asset coverage are documented. The family can still discuss allocation without inventing an apparently precise relative-return number.
05Run a Release Gate and Preserve the Correction Trail
The controller prepares an exception register before publication. For each material item, name the affected report line, source record, as-of date, financial effect if known, owner, resolution deadline and release decision. The CIO or investment committee reviews the performance interpretation; an authorized family-side approver signs off on the report's audience and any provisional wording. Approval roles should follow the family's own policy rather than an assumed universal job title.
For Rowan, a compact close record might read:
| Item | Status at 31 December | Owner and release treatment |
|---|---|---|
| Liquid-sleeve contribution and 11.69% illustrative TWR | Illustrative flow and math checked; real fee, source and scope checks pending | Controller clears checks; committee reviews interpretation |
| Private-fund NAV | Latest approved statement dated 30 September; 31 December value unknown | Alternatives lead requests the new statement; label the December value unknown and hold a current consolidated return |
| Benchmarks | Liquid comparator awaiting documented fee/currency match; private comparator unavailable | CIO approves a like-for-like comparator or removes relative-return claim |
| Report release | Pending exception decision | Authorized approver decides which pages can be issued and which are held |
Case verdict: On these fictional statuses, the full 31 December performance pack is not approved for release. The output decision is specific:
| Proposed output | Issue or hold on the stated facts? | Proof that changes the decision |
|---|---|---|
| Source-dated holdings and exception memo | May issue only with authorized approval and a prominent mixed-date label; December private value remains unknown | Approver signs permitted wording, audience, date and version |
| Liquid-sleeve performance page | Hold the real return; 11.69% is illustrative only | Controller clears source, fee and perimeter checks; committee reviews interpretation |
| Current consolidated performance return | Hold | Approved December private value or an expressly approved alternative valuation policy and recalculation |
| Benchmark-relative claim | Hold | CIO approves a comparable benchmark, period, currency and fee basis |
The office logs what it issued, to whom, under which version and with which open items. When a later private statement arrives, it creates a new source-dated calculation and release decision; it does not silently overwrite the earlier memo.
If a late fund statement changes a published figure, preserve the original pack, new source, recalculation, reviewer approval, version and notice to recipients. Do not overwrite the record and leave the family to guess why last month's return moved. A correction log should identify whether the change came from a new valuation, data error, methodology change or scope adjustment.
The report succeeds when it makes the next decision safer: where to allocate, whether to rebalance, which manager question to ask and what information must arrive before the family acts. A return becomes useful only when its scope, date, method and unresolved qualifications travel with it.
 Investment & Portfolio · Analysis
What Is Family Office Private Fund Commitment Pacing, and Why Does It Matter?
Private fund commitment pacing sets the size and timing of new promises while older funds can still call… Investment & Portfolio · Analysis
Family Office Private Asset Valuation Policy: Which Mark Belongs in the Report?
A December family report can contain a fund value dated September and a direct-company mark proposed from a… Investment & Portfolio · Analysis