Where Does a Correction Go After FundCount? Compare Alternatives Through the First Close
Compare seven FundCount alternatives by the job each could take over. Follow one NAV correction through the books, family report and first close.
An alternative to FundCount can do two different jobs for a family office: take over the legal-entity books, or improve investment reporting while FundCount continues to hold them. The choice determines where an amended valuation is approved, how it reaches the family report, and who reconciles the two records. The seven candidates fall into two demo routes, each judged against the same illustrative correction and first-close test. We have not tested or ranked these research-based candidates.
- Map what FundCount does in your office: entity general ledger, investment records, consolidation, reporting and portal. A replacement must cover the jobs you intend to move.
- For each entity, decide whether its books move. Map the investment records and reports that depend on them. Where the books stay, require a named owner and a reconciliation from the corrected investment value to each affected report.
- Give shortlisted vendors the same illustrative $50,000 NAV correction below. Treat a polished report as incomplete evidence until you have the posting, book-to-report reconciliation, approval history, recipient access and reissued version.
01What Are You Replacing in FundCount?
Map the Books, Investment Records, Reports, and Portal
FundCount describes portfolio, partnership and general-ledger accounting alongside data aggregation, consolidated reporting and an investor portal for family offices. That broad description does not establish which modules an individual customer buys or configures. Before looking at alternatives, mark which system currently owns each record and which outputs your team relies on.
| Current job | Identify the authoritative record | Ask for the present output |
|---|---|---|
| Legal-entity books | Chart of accounts, journal entries and approved period balances | Trial balance and entity financial statements |
| Investment records | Positions, cash flows, valuation dates and investment performance | Holdings and valuation history |
| Consolidation | Ownership, intercompany entries and eliminations | Family-level consolidated or net-worth view |
| Reporting and access | Approved calculations, report versions and recipients | The report each family member or adviser receives |
The answer may differ by entity or asset class. A family office with outsourced bookkeeping might use FundCount principally for investment and family reporting; another might post its own entity books there. Assign the proposed route to each affected entity, investment record and report before calling any vendor a replacement.
Decide Whether the Accounting Core Stays or Moves
If the entity general ledger moves, the new arrangement needs opening balances, historical transactions, journal approval, consolidation and a controlled close. A dashboard that ingests balances cannot establish those duties by itself. If the books stay, the reporting product needs a traceable feed and a reconciliation to the approved carrying values. Either architecture can be sensible; the source of truth and handoff owner must be explicit.
Use a one-page ownership map: source statement → investment value → entity books → reconciled report → approved recipient. Write the system, person and approval for each arrow, by entity or asset class where authority differs. A policy-dependent NAV-to-book difference belongs in that reconciliation. This shows where a correction could stop, duplicate or appear without authority.
When Is This a Family-Office Decision Rather Than Pooled-Fund Administration?
This shortlist is for a US family office managing its own entities and investment reporting. A pooled-fund manager may also need capital accounts, allocations, waterfalls, classes or series, administrator oversight and investor notices. FundCount's package descriptions distinguish fund-administration and private-fund work from its family-office offering. If those pooled-vehicle duties are the buying trigger, scope them separately; our fund reporting software comparison examines that adjacent job. Similar report screens do not establish equivalent fund-accounting coverage.
02Where Does a Corrected Valuation Go?
Illustrative Case: A Late Private-Fund NAV Correction
Use one small, fixed case to expose the accounting-to-report handoff. The family owns 100% of the holding entity, and that entity holds all of the family's position in one private fund. There is no outside interest in the entity, duplicate position or foreign-exchange movement. A statement received July 15, 2026 values the position at $1.20 million as of June 30. The family report is approved July 31. A corrected statement arrives August 5, still effective June 30, with NAV $1.25 million. The investment-record change is +$50,000. For this shared test, the office's written policy recognizes the corrected NAV in the June 30 entity books under either system arrangement. The correction is approved August 6 and a corrected family report is issued August 7.
| Record | Before | After correction | Required explanation |
|---|---|---|---|
| Source-statement NAV | $1,200,000 | $1,250,000 | Retain both dated statements and the effective date. |
| Investment NAV register | $1,200,000 | $1,250,000 | Show who accepted the replacement value. |
| Entity-book carrying value under the fixed test policy | $1,200,000 | $1,250,000 | Show the $50,000 journal in whichever GL owns the entity books. |
| Approved family report NAV | $1,200,000 | $1,250,000 | Identify superseded and reissued versions and recipients. |
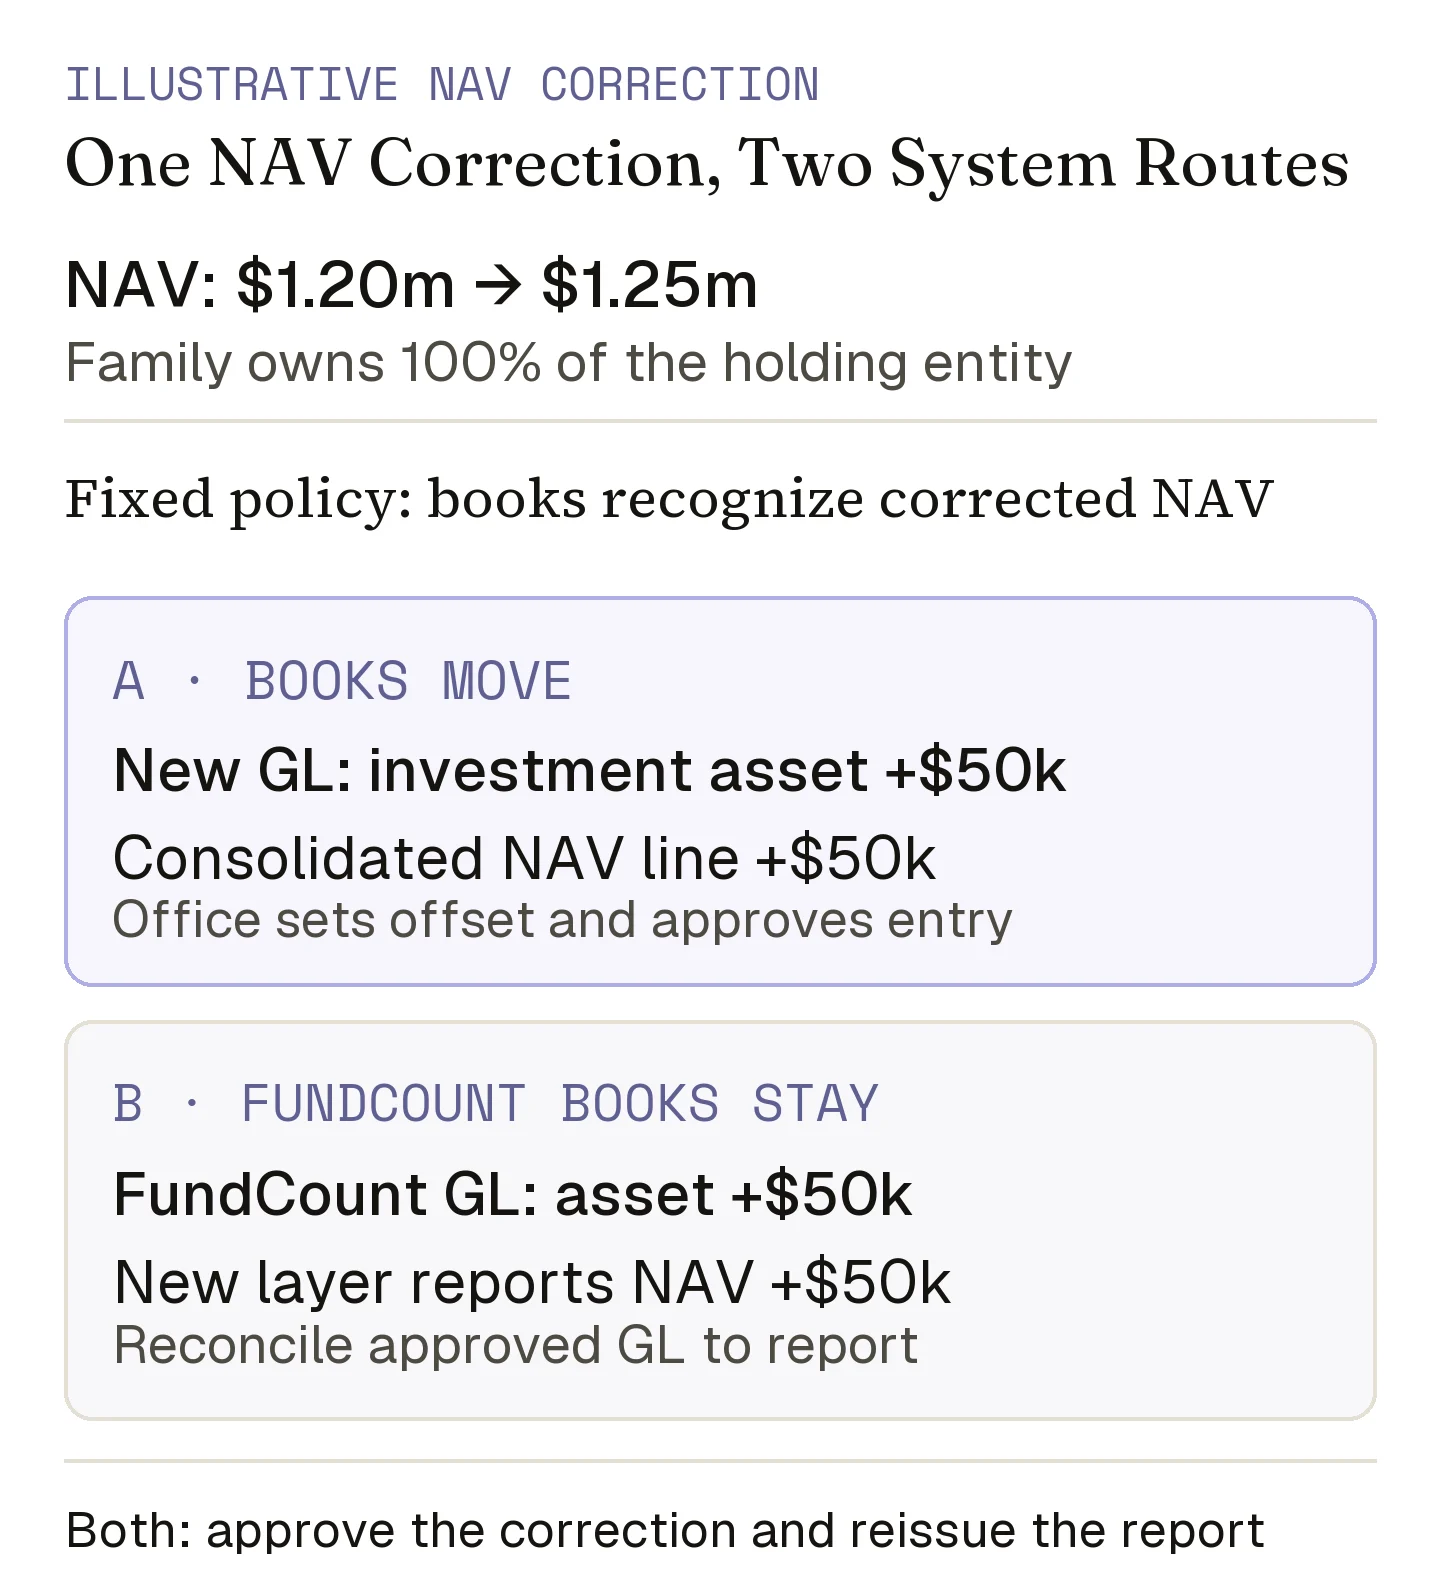
These are illustrative expected outputs for a wholly family-owned entity under one fixed book policy. No candidate has run this test. Both routes need recorded approval, reconciliation and a versioned report reissue.
Before a demo, the accounting lead must state the book basis, offset account, period policy and reporting basis. Keep those rules the same for both routes; only the system that owns the posting and the reporting handoff changes. Ownership percentage, duplicate positions, FX, taxes or other adjustments would change the expected result. The demonstration must use the agreed inputs and disclose any different assumptions.
If the Books Move: Posting, Consolidation, and Approval
Under Route A, the replacement GL owns the June 30 entity books. Under the fixed policy above, its expected entry raises the entity investment asset by $50,000; the accounting lead must specify the offset account and June-period treatment in the test instructions. Because the family owns the entire holding entity in this example, and there are no other adjustments, the consolidated investment-NAV line rises by $50,000. Check any net-worth or performance total under the office's reporting policy. The demo must show the effective-date treatment, journal, approval, period controls and consolidation trace. The old report should remain accessible as superseded, and the August 7 version should reach only approved recipients.
A numeric total alone cannot prove the close. The accounting lead should be able to trace the $50,000 from the corrected statement through the investment record, booked entry, consolidation and final report. If a closed period cannot be reopened, the team must agree how the adjusting entry and comparative report are handled before evaluating a demo.
If the Books Stay: Feed, Reconciliation, and Report Reissue
Under Route B, FundCount remains the formal book authority, so FundCount's GL posts the same $50,000 investment-asset correction required by the fixed policy. The new reporting layer must receive the approved corrected value and effective date, reconcile its investment NAV to the FundCount book balance, and show the $50,000 change in the family report. The GL owner approves the entry; the reporting owner approves the reissue. Keeping the books in FundCount does not make the book change $0 under this policy.
A different written book policy is a separate scenario, not a Route B advantage or drawback. If the office instead keeps a $1.00 million carrying amount unchanged while reported NAV moves from $1.20 million to $1.25 million, the legal-entity GL change is $0 under either system arrangement and the NAV-to-GL bridge moves $200,000 → $250,000, absent other adjustments. In that scenario, the book owner documents why no entry is posted and the reporting owner signs the bridge. Run both architectures against that same second policy if it reflects the buyer's actual books; do not compare one architecture's $50,000 entry with the other's $0 entry as a product result.
The reporting demonstration should show how the amended statement enters, how a superseded value is identified, where exceptions appear, and how the revised report is versioned and distributed. The accounting owner signs the GL-to-report reconciliation under the fixed policy, or the documented NAV-to-GL bridge under the second policy. If FundCount itself holds both the books and an investment register, specify which value feeds the new layer to prevent a duplicate correction.
03How Were the FundCount Alternatives Shortlisted?
Compare the Same Job Across Unlike Products
The seven names below have current vendor descriptions relevant to family-office accounting, investment data or reporting. They are grouped by the role to investigate; we have not assigned universal scores. We used a dated US search-results sample to find the questions buyers encounter, then checked each included product against its own primary material. No hands-on test or buyer-specific US proposal has been completed.
The same questions apply to each: What record can it own? How does a backdated source correction reach the books and reconciled family report? Which approval, report-version and access controls can be observed? Which modules, integrations, service duties and US terms are in the written scope? A vendor's silence on a page leaves a capability unknown; it does not establish absence.
Compare Each Vendor's Role, Correction Handoff, and Unknowns
| Product | Vendor-described role | Book authority to verify | Correction/control demo needed | Contract and first-close proof needed |
|---|---|---|---|---|
| Asset Vantage | GL, aggregation, consolidation, performance reports | Can quoted GL own this entity's approved books? Unknown | Observe entry, approval, report version and access | Confirm US modules; reconcile migrated close |
| Archway | Family-office/fund GL, feeds, entity reports and services | Which system and operator own this entity's books? Unknown | Observe preparer, approver, reissue and access | Assign software/service duties; reconcile migrated close |
| Eton Solutions AtlasFive | GL, entity, trust/partnership accounting, reports | Are the required posting modules in scope? Unknown | Observe entry/allocation, approval, reissue and access | Confirm modules/history; reconcile migrated close |
| SumIt | Bookkeeping, inter-entity journals, statements | Can it own this entity's approved books? Unknown | Observe valuation input, entry, approval, report version and access | Confirm feed and US quote; reconcile migrated close |
| Addepar | Investment aggregation, ownership views, reports, GL integration | Retained FundCount books proposed; actual feed authority unknown | Observe GL-to-report reconciliation, approval, reissue and access | Specify GL interface; reconcile migrated close |
| Aleta | Investment ledger, specialist-GL flows | Legal-entity GL owner unknown | Observe ledger-to-GL or bridge, approval, reissue and access | Assign reconciliation; reconcile migrated close |
| Masttro | Asset/entity map, feeds, reports | Formal posting-GL role unknown | Observe source version, reconciliation, approval, reissue and access | Specify feeds and US scope; reconcile migrated close |
Every demo and contracted-close cell above states proof still needed; none records a pass. A product's inclusion does not establish that another candidate lacks a capability.
04Which Alternatives Could Take Over the Books?
The following products describe accounting functions that make a replacement conversation reasonable. The decisive question is whether the specific quoted configuration can become the approved legal-entity record and complete the first close with your data.
Asset Vantage
Asset Vantage describes a general ledger combined with data aggregation, multi-entity consolidation and performance reporting. That combination is worth investigating when the office wants fewer handoffs between entity books and investment views. The illustrative correction demonstration should trace the dated valuation source, journal, approval, consolidation impact and reissued report. A linked dashboard is insufficient if the office needs a posting GL. The vendor's public pricing examples are in INR; they do not establish a US implementation or comparable US price. Obtain the modules and services in the proposal.
Archway (Formerly SEI Archway)
The former SEI Family Office Services business became Archway after its 2025 acquisition. Archway describes a family-office and fund GL, feeds, entity views and reports, alongside outsourced operations. Its distinctive buying question is who performs the correction: your accounting staff, Archway's service team or both? Require a live trace with named preparer, approver and report-reissue owner; the contract should assign those same duties. The existence of a service offering does not establish that it is included or that Archway approves your books.
Eton Solutions AtlasFive
AtlasFive describes general-ledger, entity, trust and partnership accounting, documents and reporting. Its integrated partnership-accounting description is relevant when the family's structures require more than a simple entity GL. The demonstration should show the corrected private-fund value through the modules in the quote, including the entity posting, any partnership allocation affected, and the consolidated family output. Whether those modules, historical data and permissions are included is a proposal question; the product page does not prove the buyer's cutover.
SumIt
SumIt describes family-office bookkeeping, inter-entity journal entries, ownership-based consolidation and financial statements. It merits a test when entity structure and intercompany accounting dominate the replacement job. The same late NAV statement should reveal how the valuation enters the books, how a closed period is controlled, and how the entity change affects a consolidated statement. Its page does not establish the required investment-data feed, a US package price or a passed migration; request those details in writing.
05Which Alternatives Could Add Reporting While the Books Stay?
These products describe investment-data and reporting roles that can be evaluated with FundCount continuing as the formal book authority. They may offer other capabilities, but the reviewed pages do not settle whether a specific implementation can replace your entity GL. Test the retained-books architecture first and invite a wider accounting demonstration only if the vendor claims one.
Addepar
Addepar's family-office page describes investment data from multiple sources, ownership look-through, reporting and integration with existing general ledgers. That makes it a candidate when the office's issue is seeing and explaining investments across entities while the accounting core stays. Show the $1.25 million corrected NAV beside the approved book carrying value and the reconciliation between them, including any policy-dependent difference. The demonstration should identify which value and effective date the GL integration sends or receives. An integration claim does not by itself establish a reconciled report or replacement posting authority.
Aleta
Aleta describes a double-entry investment ledger and flows to specialist third-party general ledgers. That ledger distinction matters because an investment record can improve transaction and valuation traceability without becoming the family's legal-entity books. Determine whether this configuration sends a journal to FundCount, receives an approved balance from it, or maintains a bridge for reporting. Assign one owner to resolve any mismatch. Aleta advertises starting pricing on its own comparison page, but the advertised figure and go-live period are not a verified US contract or a comparable full-project cost.
Masttro
Masttro describes an asset/entity map, direct feeds, alternatives data and consolidated reporting. It is worth testing when the gap is visibility across holdings and ownership structures. Both statement versions should show how the old value is superseded, how an exception is approved, and which family reports and recipients change. Formal posting-GL capability remains unverified from the reviewed family-office material. Its pricing page requests a tailored proposal, so the buyer needs a US scope and quote.
06What Must Pass at the First Close?
Reconcile Opening Balances, History, and Exceptions
A vendor demo can establish that a workflow is possible in a sample environment. Migration sign-off requires the buyer's own data and approvals. Before cutover, export the agreed FundCount balances, investment positions, ownership structure, valuation history, report versions and access-state inventory. Map each user's entity/report rights into the proposed arrangement; identify permissions to carry forward, revoke or restrict. Reconcile the records to the new arrangement at the same date. Test authorized and unauthorized retrieval of historical and corrected reports, then obtain the security and reporting owners' sign-off. Classify each break by cause, owner and resolution in a shared exception log.
For Route A, compare opening and closing trial balances, entity statements, investment records and consolidated totals. For Route B, reconcile the retained FundCount books to the new investment values and reports. In both routes, check that historical as-of values stay available, role permissions are correct and the corrected statement does not create a duplicate position.
Prove the Correction Reaches Approved, Reissued Reports
Give every finalist the same statement pair, dates, 100%-family-owned holding entity and one written accounting policy. The table applies the fixed policy that recognizes corrected NAV in the entity books. The table sets sample-demo expectations; the written contract and migrated first close need separate evidence. If a real entity has outside owners or follows the separate unchanged-book policy, recalculate the expected values for both routes before using this gate.
| Gate | Route A: books move | Route B: books stay |
|---|---|---|
| Numeric output under fixed policy | Replacement GL investment asset and consolidated investment-NAV line rise $50,000; identify the offset account | FundCount GL investment asset rises $50,000; new layer reports corrected NAV +$50,000 and reconciles to the approved book balance |
| Control trail | Source, effective date, replacement-GL journal, approval, period treatment and consolidation trace | Source, effective date, FundCount GL journal/approval, feed, reconciliation and reporting approval |
| Reissue | July report marked superseded; August 7 corrected version and authorized recipients traceable | Same reissue and access evidence, with the FundCount approved book balance identifiable |
Keep three evidence states for each candidate: sample demo, signed module and responsibility scope, and migrated parallel close. Mark the demo Pass when its observed numbers and controls match the agreed test. Mark written scope Pass when the signed agreement or statement of work names the required modules, interfaces, service duties, preparer, approver, reconciliation owner and report-release owner for the quoted configuration. An unsigned proposal remains Unknown for this phase. Mark the migrated close Pass when reconciled buyer data, approvals, access checks and the report reissue are evidenced. For any phase, use Unknown when its proof is missing and Fail when an observed result contradicts its agreed rule. An old value in the reissued report, for example, fails the relevant phase.
Mark the overall first-close gate Pass only when all three phases pass, exceptions are resolved within agreed tolerances, and the accounting, reporting and security owners sign off. If any observed contradiction remains unresolved, the overall gate is Fail. Otherwise it is Unknown while any required proof or sign-off is missing. A sample demo may pass while the overall first-close state remains Unknown. This buyer acceptance record does not rate any product.
Agree on Parallel-Run Sign-Off and Ownership
Run at least one agreed close in parallel under the office's own risk policy, comparing outputs and closing each exception. Set the cutover date and closing period in the implementation plan, then replay the June correction in that first parallel close against the agreed policy. The accounting lead approves the legal-entity books or, under an unchanged-book policy, the book-to-NAV bridge. The reporting owner approves the revised report and recipients; the security owner signs off access and historical retrieval. The project owner authorizes cutover only after those owners agree the parallel-run evidence is complete. Put the test dates, tolerance rules, exception owner and fallback procedure in the implementation plan. A clean sales demo, a signed contract and an actual first-close approval are three different pieces of evidence.
07What Should a US Proposal Include?
Price the Modules, Data, Implementation, and Services
Have each finalist price the same family-office scope: number of legal entities, users, investment accounts and feeds; required accounting, partnership, consolidation and reporting modules; history to convert; reports to rebuild; hosting, support, implementation and outsourced services. Request one line per module, feed, converted year, report, implementation task and ongoing service, with quantity, one-time fee, annual fee, exclusions and responsible party. Separate one-time work from recurring charges and name what happens when entity or feed counts grow. A quoted software license and a managed accounting service are different cost categories.
The public pages do not supply comparable US total costs across all seven candidates. FundCount's current family-office pricing page displayed a $35,899-per-year starting figure when checked on October 14, 2026, plus digital-transformation and hosting fees; confirm the billing currency and current US package directly. Asset Vantage's visible examples are INR, and other vendors describe tailored or incomplete pricing. Do not rank total cost from those fragments.
Name the Owner of Each Accounting and Reporting Handoff
The written proposal should answer five operational questions: Who accepts the corrected source? Who can post the entry? Who approves the entry or policy-dependent NAV-to-book difference? Who reconciles the investment and entity views? Who can revoke, reissue and distribute a report? Put the provider, office, administrator and any outsourced operator in separate columns. If responsibility is shared, specify the escalation and evidence each side must retain.
The same handoff map belongs in the services agreement and the parallel-run plan. A vendor's ability to produce a report does not settle who owns its accounting basis or who signs its release.
08Which Path Belongs on Your Demo Shortlist?
If FundCount's Books Must Move
Begin with Asset Vantage, Archway, Eton Solutions AtlasFive and SumIt as accounting-core investigations because their current descriptions include relevant general-ledger or family-office bookkeeping functions. Shortlist only those willing to demonstrate your exact entities, accounting policy, historical conversion, correction entry and first-close controls in the quoted configuration. Archway also requires a clear software-versus-service split. No public page establishes that any of the four has passed this migration.
If the Books Can Stay
Begin with Addepar, Aleta and Masttro for the investment-data and reporting layer, while retaining FundCount as the named book authority. Give each the same NAV correction and demand a visible GL-to-report reconciliation, exception workflow and report reissue. Aleta's investment-ledger claim deserves a specific question about journal ownership; Addepar's GL integration needs direction and reconciliation proof; Masttro's asset/entity map needs source-version and recipient proof. Move a candidate into a replacement evaluation only if its proposed configuration demonstrates formal books as well.
Assign the route by entity, investment record and report, then send each finalist the same case and proposal worksheet. A successful sample demo advances a candidate to contract and migration checks. The new arrangement is ready only when signed responsibilities and the migrated parallel-close result support the accounting, reporting and security owners' sign-off.
The coming shake-out in family-office software
The category has never been more crowded. Consolidation is coming — and the firms that survive will be… Knowledge & Decision · Analysis
Is a Multi-Family Office Right for Your Family? Compare Fit, Fees and Services
Compare multi-family office fit, services, fees and family responsibilities with an illustrative quote worksheet and provider-check questions. Knowledge & Decision · Analysis