Family Office Trust Accounting Before the Trustee Signs
The family office's consolidated report says the trust has US$101,000 in cash. The bank agrees.
The family office's consolidated report says the trust has US$101,000 in cash. The bank agrees. Yet the proposed beneficiary account still has an open decision: a US$4,000 fee has left the bank, but no one has approved whether it belongs against fiduciary income, principal, or both under this trust's governing rules.
Family office trust accounting is the trust's own record of assets, receipts, disbursements and the treatment that affects beneficiaries. It must reconcile to cash and investments, but a matching bank total is only one condition. The trustee needs a supportable allocation, the authority behind each distribution and a report that can be traced to source transactions.
- Keep a separate trust-level record tied to the governing instrument, legal owner and period. A family-wide dashboard cannot decide who is entitled to trust income or principal.
- Reconcile the bank balance and each fiduciary classification. In the case below, cash closes at US$101,000 while a paid US$4,000 fee still prevents final allocation.
- Before ordinary release, resolve open treatments, update the schedules, independently check the bridge and confirm the recipients and period. If a legal accounting deadline arrives first, the trustee, with counsel as needed, must determine timely disclosure and any later correction.
01What Family Office Trust Accounting Must Record
A trust account follows property held under a particular trust. Its recurring job is to show the opening position, what came in, what went out, what remains, and how each movement affects the interests established by the governing instrument and applicable law.
For an office supporting several trusts, build the record per trust and reporting period. A useful control line contains the trust's legal name, trustee, account and custodian identifiers, source document, posting date, asset or cash movement, proposed principal/income treatment, approver, reconciliation status and beneficiary-report destination. The source link belongs with the line item; a polished report without it is hard to check.
The governing instrument, jurisdiction, beneficiary interests and any court order determine the actual duty and recipient. As one concrete example, California Probate Code §16063 describes information in an account furnished under that state's §16062. It includes principal-and-income receipts and disbursements, assets and liabilities, trustee compensation and agents.
Section 16062 also sets qualified timing and recipient rules. These California provisions show questions to map; other jurisdictions and trusts require their own review. An internal exception cannot suspend a legally due account.
The Trust's Record Has Two Tests
The balance test matches cash and investments to bank and custodian records, and liabilities to invoices or other obligation records, at the same as-of date. The fiduciary test asks whether receipts, expenses and distributions are classified and authorized under this trust's rules. Either can fail while the other passes.
Principal and income are fiduciary accounting categories. They answer a different question from bank cash or taxable income. California's fiduciary income and principal statute illustrates that allocation layer. The applicable trust instrument and jurisdiction must be checked before using any particular treatment. The family office should record who made that determination and what document supports it.
02Which Records Belong to the Trust Rather Than the Office?
An office may pay staff, hold its own operating cash and compile a consolidated family view. A trust may own securities, receive income and make beneficiary distributions. A shared dashboard should preserve their separate legal owners and accounting purposes.
| Record | Question it answers | Owner of the decision or review |
|---|---|---|
| Trust fiduciary account | What did this trust receive, spend, hold and allocate between principal and income during the period? | Trustee or properly authorized fiduciary decision-maker; preparer and reviewer identified |
| Entity general ledger | What does a family company, partnership or office entity own, owe, earn and spend? | That entity's assigned accounting and approval roles |
| Consolidated family report | What does the family want to see across owners and periods? | Report owner and approver; must preserve source and as-of dates |
| Trust tax workpaper | What amounts need review for the trust's tax return and beneficiary tax reporting? | Tax preparer and fiduciary signoff under the applicable filing facts |
Office staff may prepare the trust ledger; the authorized fiduciary retains the assigned decisions. A shared investment position does not establish ownership by the office entity. Keep account title, custody, ledger and reporting scope aligned. The family-office entity accounting guide addresses the entity ledger; this article owns the fiduciary account and its beneficiary-facing release.
03Follow One Trust Receipt, Distribution and Fee
This illustrative cash-only exercise uses a fictional Trust T-01 and a proposed accounting period of 1 October 2025 to 30 September 2026. The trustee must confirm the actual required period and recipients. The trust begins with US$100,000 cash recorded as principal.
A US$12,000 interest receipt reaches the trust bank account. For this case, assume the trustee, after adviser input on the governing instrument and applicable law, approves its classification as fiduciary income. The trustee then authorizes and pays a US$7,000 income distribution to a beneficiary whose right to this distribution has been checked against the instrument. Those eligibility and approval assumptions apply only to fictional Trust T-01.
A US$4,000 administration fee is also paid during the period. Assume the invoice and bank debit are documented in this fictional example, but its allocation between principal and income has not been approved. No software category or default percentage can settle the question on its own.
| Cash movement | Bank effect | Fiduciary-account status | Evidence to keep |
|---|---|---|---|
| Opening trust cash | US$100,000 | Principal opening amount, assumed verified | Prior signed account and bank opening position |
| Interest receipt | +US$12,000 | Income under the stated, approved case assumption | Bank credit, source statement and classification decision |
| Beneficiary distribution | −US$7,000 | Income distribution under the stated approval | Trustee authorization, payee, bank debit and receipt check |
| Administration fee | −US$4,000 | Paid, allocation unresolved | Invoice, bank debit, applicable rule and decision owner |
| Closing trust cash | US$101,000 | Cash agrees with the bank; account remains provisional | Dated bank reconciliation and open-item log |
A Bank Balance Can Reconcile While the Account Stays Open
The bank cash proof is:
US$100,000 + US$12,000 − US$7,000 − US$4,000 = US$101,000.
Before resolving the fee, the allocated lines show US$100,000 principal and US$5,000 income after distribution. This is a cash reconciliation bridge, not a final beneficiary allocation:
| Provisional bridge line | Amount |
|---|---|
| Principal recorded so far | US$100,000 |
| Income recorded after the distribution | +US$5,000 |
| Paid fee, allocation still open | −US$4,000 |
| Cash tied to bank | US$101,000 |
The principal and income lines remain provisional, and the paid fee stays separately visible until the authorized decision. Assigning it silently to income or principal would make the schedule look final without approval.
The decision changes the beneficiary-facing columns while cash stays US$101,000. If the governing rules and authorized decision put the entire fee against income, the illustrative closing classes become US$100,000 principal and US$1,000 income. If they instead put it entirely against principal, they become US$96,000 principal and US$5,000 income. Neither is the answer for a real trust; a split or different treatment may apply. The point is to preserve the unapproved classification until its actual rule and decision are recorded.
This example uses cash only to make the control visible. A full trust account may also need investment positions, purchases and sales, accrued amounts, liabilities, valuations, fees and beneficiary interests. Those records need their own dated source and reconciliation. Do not present this worked cash example as a statutory form.
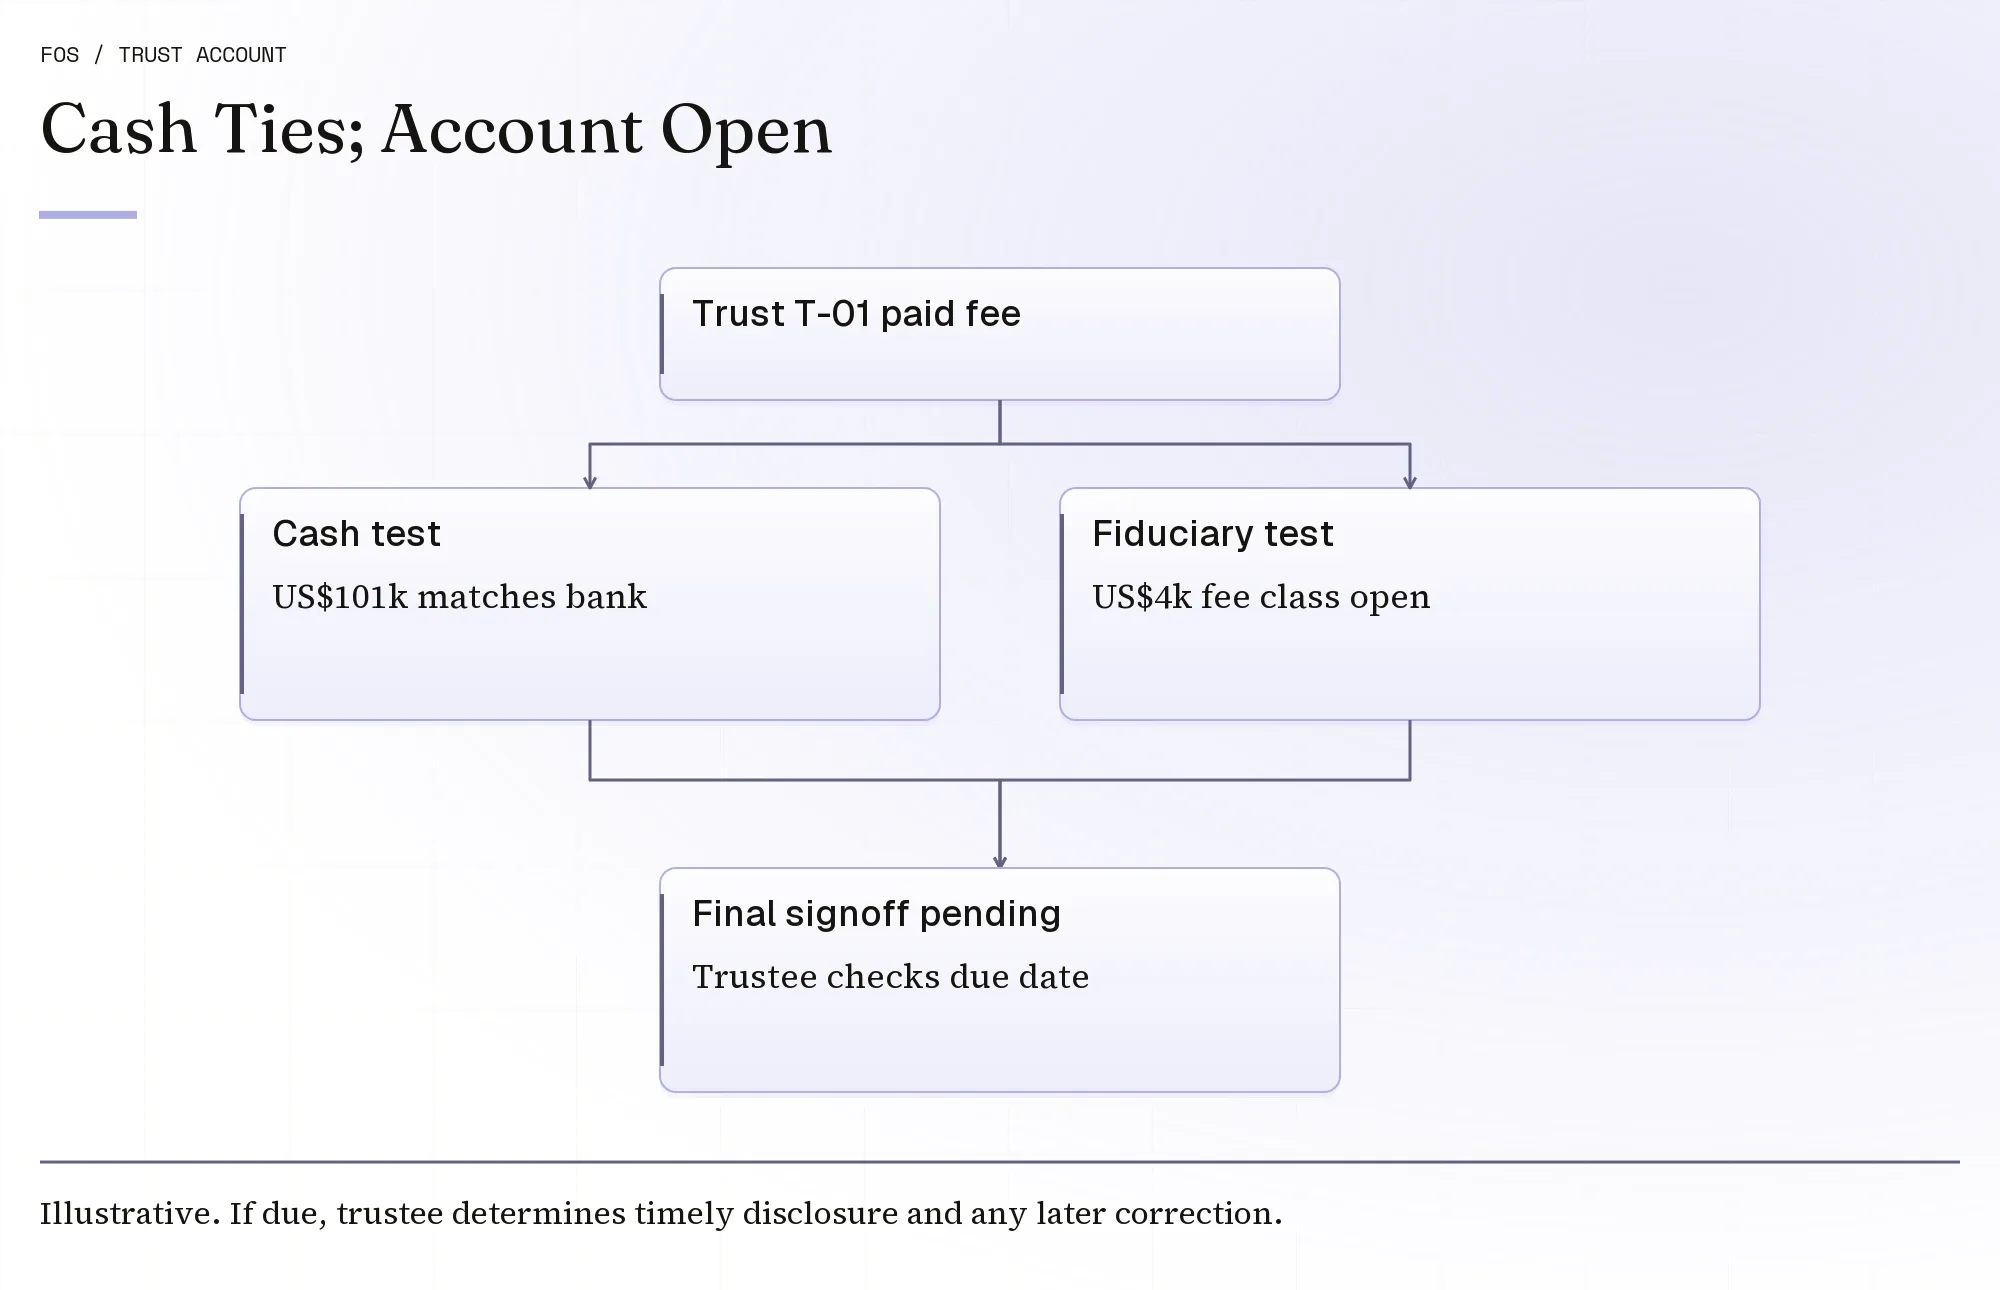
Cash reconciled, fiduciary classification open. View the wider desktop diagram. If an account is legally due, the trustee determines timely disclosure and any later correction.
Who Decides the Fee's Principal/Income Treatment?
The preparer attaches the invoice, payment proof, trust clause and applicable jurisdictional rule. The trustee or other legally assigned fiduciary decision-maker, with advice where needed, determines how to allocate the fee. The controller records that decision and its effective period; a second reviewer checks that the principal/income schedules and bank bridge now agree.
If the rule or authority is unclear, retain unknown with a named owner and next action. The fee is still a cash disbursement. It stays in the reconciliation while the office waits; a beneficiary report must identify any provisional principal/income result. A later change needs a dated correction record that preserves the earlier version. The family-office document management guide explains the separate version and authorization trail.
04What Goes Into the Trustee and Beneficiary Account?
Start with the governing requirements for this trust, then build a source-linked package for the actual period and recipients. A practical review packet can include:
- Opening and closing assets and liabilities, with the valuation and statement dates visible.
- Receipts and disbursements separated by approved fiduciary treatment, including distributions and fees.
- A bank and custodian reconciliation, with outstanding items assigned to an owner and deadline.
- Trustee and agent compensation, approvals and any conflict or exception documentation required for the account.
- A change log showing who prepared, reviewed and approved the version sent to beneficiaries.
For the worked period, the proposed packet remains provisional while the US$4,000 fee allocation is open. The trustee can see the cash reconciliation and exception note. The income/principal statement awaits an authorized final treatment.
This internal release gate does not change a legal accounting deadline. If an account is due before the question is resolved, the trustee, with counsel as needed, must decide how to meet the applicable disclosure duty on time, identify the unresolved amount and arrange any needed correction. Label provisional figures as such; do not simply wait past a required date.
California's §16063 is one example of the content a state may require. It also identifies agent compensation and information about court review. Elsewhere, the exact packet, cadence and recipients can differ. Neither an attractive dashboard nor a generic template substitutes for checking those duties against the trust's documents and jurisdiction.
05How Do Fiduciary, Entity and Tax Records Connect?
The same receipt may reach a bank feed, investment register, trust fiduciary ledger, consolidated family report and tax preparer's workpaper. Each has a different job. The bridge should carry the trust ID, source transaction, amount, date, classification status and any adjustments so that a reviewer can trace the number without making one system the authority for all others.
For the US$12,000 receipt, the office can show where the bank credit entered the trust record, the trustee's assumed approval of its fiduciary-income treatment, and how that treatment appears in the proposed account. The tax preparer receives the source and status, then applies tax rules separately.
The IRS description of Form 1041 concerns income, deductions, gains, losses and tax liability of estates and trusts. 26 U.S.C. §643(b) defines “income” for specified trust-tax subparts by reference to the governing instrument and applicable local law. The tax workpaper and fiduciary account therefore need an explicit bridge. Completion of the return leaves fiduciary-account release as a separate decision.
If a family company pays a trust expense or a trust holds an interest in that company, retain each entity's entry and the legal basis for the cross-entity amount. Preserve those entries in the bridge so the family-wide total does not erase the transaction. The accounting treatment and any tax effects need review under the actual facts.
06When Would Software or an Outside Administrator Help?
The decision turns on control failures and volume. A small, stable trust may use a controlled ledger and document repository if it can preserve classifications, approvals, source records and reconciliations. Multiple custodians, frequent distributions, varied beneficiary interests or repeated late adjustments may justify a dedicated trust accounting system or an administrator. Neither purchase nor outsourcing transfers the trustee's responsibility automatically.
Use the worked case as a vendor or provider demonstration. Ask them to:
- Import the opening balance and three transactions, keeping the paid fee unallocated.
- Reconcile the US$101,000 bank balance and show the provisional beneficiary view.
- Record an authorized classification decision and reproduce both the earlier and corrected versions, including a source-to-report export and role history.
Mark a step unknown until it is observed. Separately check contract scope, data portability, migration, security access and who signs the account in writing.
Vendors such as TrustEase and ProTrustee describe principal/income and trustee-reporting capabilities. These are supplier claims. Ask each product to demonstrate this office's case before awarding a pass. A general ledger, CRM or dashboard also needs the same control and output test before judging fit.
07The Trustee Signoff Test
The trustee's release decision needs one owned record. Here is the filled illustrative open item for Trust T-01; the actual trust's duties and evidence control the real release:
| Field | Trust T-01 case record |
|---|---|
| Period and version | Proposed 1 Oct 2025 to 30 Sep 2026; version 0.1 provisional. Trustee, with counsel as needed, to confirm actual required period and accounting deadline. |
| Legal due date and recipients | Unconfirmed in this fictional record. Trustee checks the instrument, jurisdiction, beneficiary interests and any court order; identifies the actual date and qualified recipients. The 27 Oct target below is internal, not a legal deadline. |
| Cash proof | US$101,000 bank cash reconciled in this cash-only fixture; other assets and liabilities are outside the example and remain to be checked. |
| Open decision | US$4,000 administration fee paid; principal/income allocation unknown. Invoice, payment proof, trust clause and applicable rule attached. |
| Decision owner | Trustee or legally assigned fiduciary decision-maker, with counsel/adviser input as needed; office controller prepares the corrected schedules. |
| Distribution and recipient | US$7,000 assumed authorized and paid to an eligible income beneficiary; retain instrument-supported right, trustee approval, payee and payment evidence. Confirm actual report recipients. |
| Independent check | Separate reviewer to match the corrected principal/income bridge, bank and source records; sign the reviewed version. |
| Next action and time | Trustee, with counsel as needed, confirms the due date and fee treatment. The fictional internal review target is 27 Oct 2026 or earlier if required; controller updates, reviewer checks. |
| If the legal date comes first | Trustee, with counsel as needed, decides the legally permitted timely account or disclosure path, any available extension or court procedure, the affected figures and recipient notice. Name the correction owner and trigger. Do not label an unresolved principal/income schedule final. |
| Release status | Provisional; ordinary final signoff open. A legally due account still needs timely treatment or disclosure decided by the trustee, with counsel as needed, and any later correction tracked. |
The current verdict is cash reconciled; fiduciary allocation open. After the fee decision, the preparer posts the authorized allocation, recomputes both classifications and ties them back to US$101,000 bank cash. The reviewer checks the correction, and the trustee decides on release under the governing requirements. Record the time and version.
If the fee remains unresolved near an applicable deadline, the trustee, with counsel as needed, determines timely disclosure and correction. The office keeps the exception, owner and affected figures visible in every version.
 Accounting & Reporting · Analysis
A Family Office Reconciliation Process Built Around the Open Item
A family report can agree with the investment dashboard and still be wrong. Both may have copied the… Accounting & Reporting · Analysis
How a Family Office Expense Allocation Policy Decides Who Pays
An invoice can have one payer and three beneficiaries. Paying it from the family office's bank account does… Accounting & Reporting · Analysis